Chinese accelerator delivery: 180,000 planned, 20,000 shipped
Three vendors set targets their wafers could support. What they could not control was the package, the stack and the floor.
- 180,000 / 20,000one vendor's 2026 plan for its anchor customer against what the packaging and memory queue has actually delivered, on a single supply-chain source's count
- 108 percentCambricon's first-half revenue growth, public, with the second quarter up 7.8 percent on the first and inventory at 45 percent of total assets
- 20 to 30 percentreported HBM3E yield at the domestic memory maker, against about 70 percent at the market leader, at mass production late in Q4 2026
- 2packaging houses in stable high-volume production nationwide, which is the ceiling every shipment target is written against
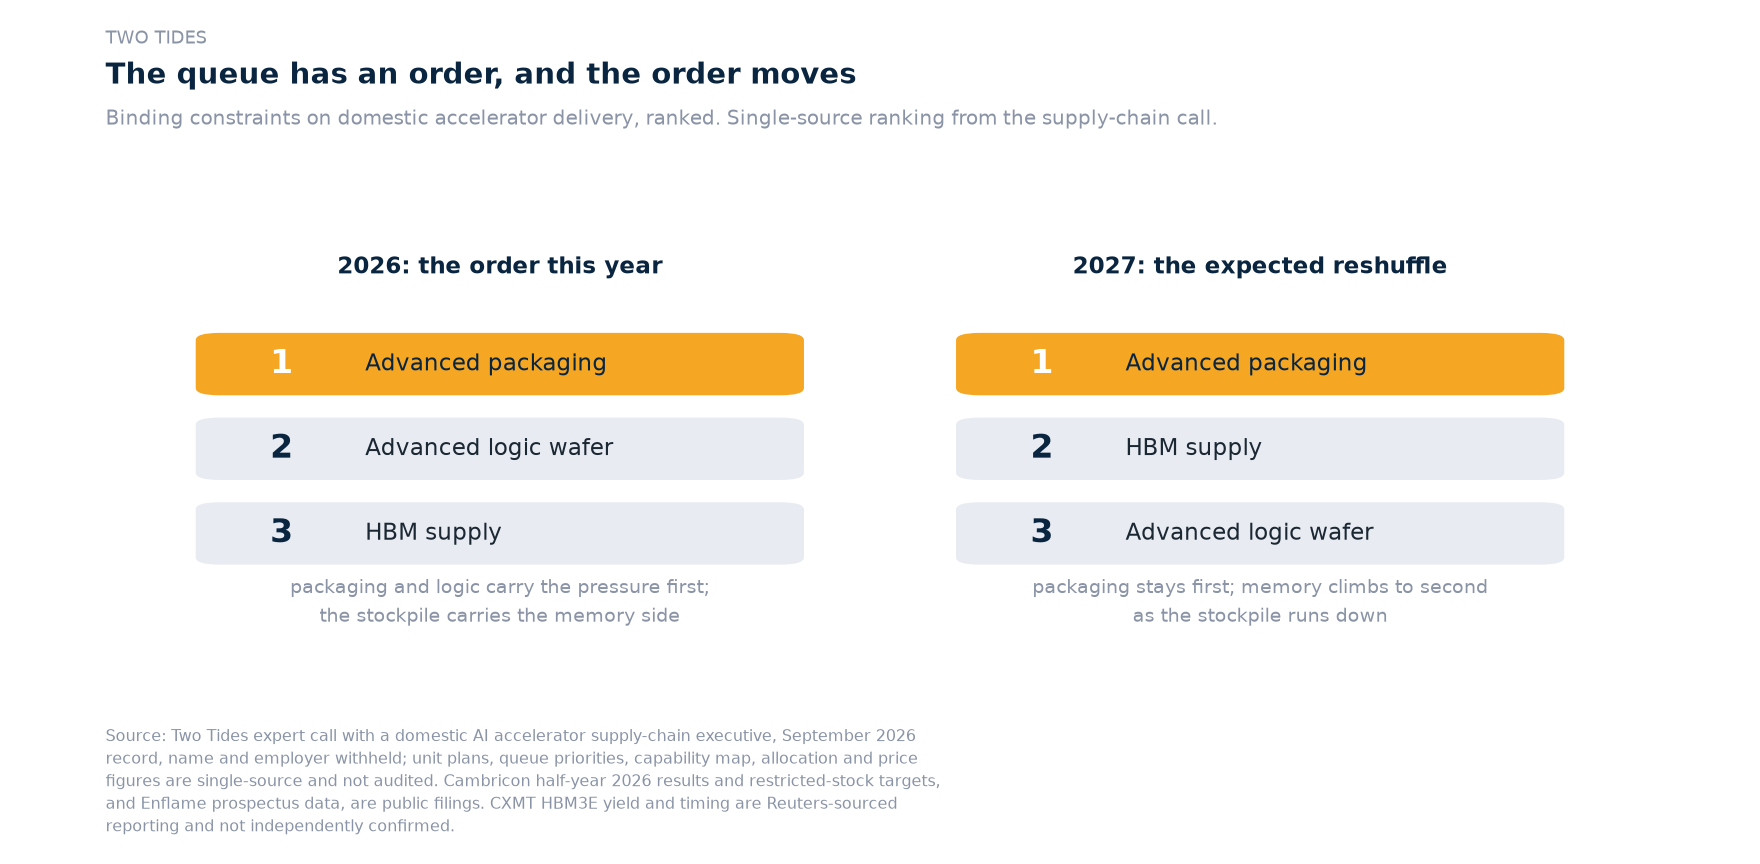
Every accelerator target published this year was written as if the package and the memory would be there. The queue below the fab is where those targets meet arithmetic: the die-to-wafer bonding that turns a large die into a working part, the wafer line running at partial allocation to a single customer, and the HBM stack that has to arrive before a card can ship. A single source on the domestic supply chain ranks the constraints for 2026 as advanced packaging first, advanced logic wafer second, HBM third, and expects the order to change next year: packaging still first, memory climbing into second as the stockpile that carried this year is drawn down and the domestic replacement ships at half the incumbent yield or less.
The delivered number
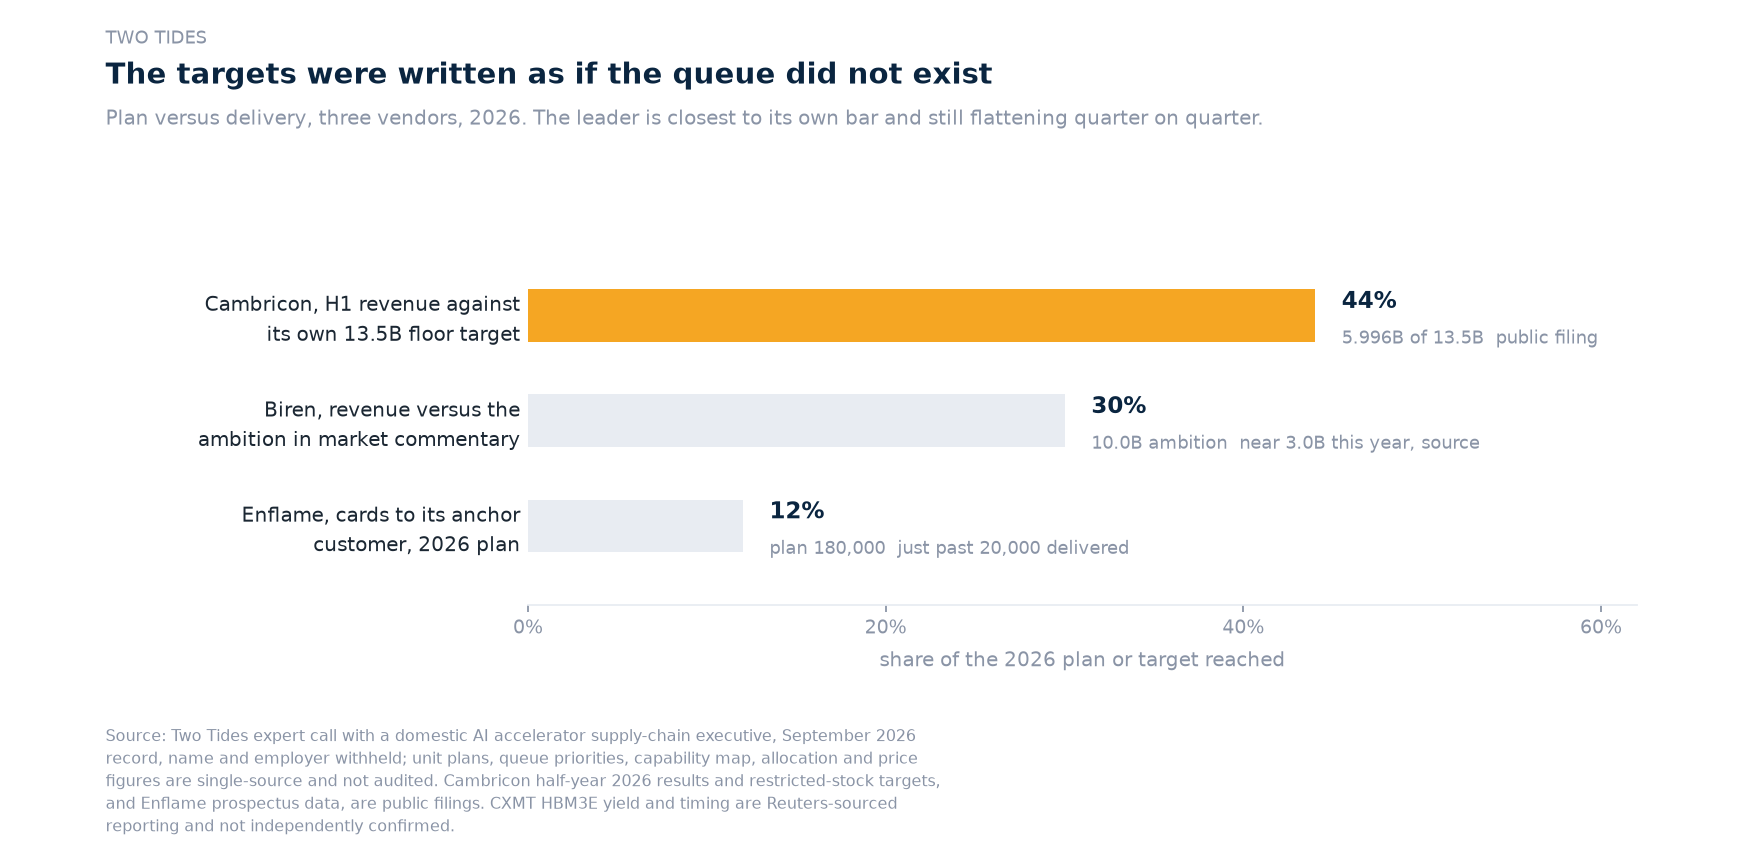
The gap between plan and delivery is visible from outside the supply chain. One vendor went into 2026 planning about 180,000 cards for its anchor customer and has delivered just past 20,000. A second carries a ten billion yuan ambition in market commentary that the same source puts near three billion this year and a little over five next. The market leader's half-year report is public and explains why the queue is the honest layer: revenue up 108 percent year on year, but the second quarter up only 7.8 percent on the first, with inventory at 8.248 billion yuan, 45 percent of total assets and mostly raw material and consigned work in process. That is the balance sheet of a company that has paid for the inputs of cards it cannot yet finish.
| Vendor | Stated plan | What the queue allows |
|---|---|---|
| Enflame | about 180,000 cards to its anchor customer in 2026 | just past 20,000 delivered; near 400,000 committed for 2027 |
| Biren | a ten billion yuan ambition in market commentary | near 3.0 billion this year, a little over 5 next |
| Cambricon | 13.5 billion yuan floor in its own restricted-stock plan | 15.0 to 18.0 billion on the source's estimate, gated by the flagship part |
Plan and delivery. The first two rows are a single source's estimates; the third row's floor is a public filing.
What the memory side adds
The domestic memory maker has qualified HBM3E and is reported to reach mass production late in the fourth quarter at 20 to 30 percent yield, against about 70 percent at the market leader, shipping parts closer to the previous generation in performance. Designers have taken samples; volume is small. Until it is not, buyers who planned around stockpiled HBM pay a second-half quote five to six times the year-ago period for parts already sitting in a warehouse. The wafer line is the third constraint: twelve- inch advanced output a little above 30,000 wafers a month, year-end 50,000 judged unlikely, large-die yield of 30 to 40 percent, and roughly 40 percent of that allocation going to one customer on the source's estimate.
None of this is a forecast about demand. It is a statement about how many finished cards the floors can produce, and every target above that number is an option on capacity someone else controls.
The call behind these numbers runs twelve questions: the order of the constraints, each vendor's plan against its delivered count, the balance-sheet shape of the leader, and what the memory side adds next year.
Read it in Two TidesThis page is the public data companion to The Call 06 in Two Tides. The conversation itself, with the vendor-by-vendor detail and the source's own caveats left in, is the post in the letter.
Research, not advice. This page is research and commentary on an industry. It is not investment, legal or engineering advice, and not a recommendation to buy or sell any security. Figures are the best estimate available at the time of writing; where one rests on a single source, the text says so.
Cite this page as: Quorsio, "Chinese accelerator delivery: 180,000 planned, 20,000 shipped", November 2026, with a link to this URL. Short excerpts with attribution are welcome. Republishing the page in full, including its tables and charts, needs written permission: hello@quorsio.com.