Ascend's 2027 shipment forecast: three scenarios and the yield line that picks one
The near-doubling to 2.8–3.0 million chips is not a demand forecast. It is a statement about one process curve, and one point of yield is worth 50,000 chips.
- 2.8–3.0MAscend chips quoted for 2027 — a near doubling that is a yield forecast, not a demand forecast
- 65–67%die yield next year the neutral case rests on, from 40–50% today; TSMC's N+1 sits near 80%
- 50,000chips gained or lost per single point of yield on a 5 million die base
The forecast that will be quoted in February puts Ascend shipments at 2.8 to 3.0 million chips in 2027, close to double the 1.2 to 1.6 million expected for 2026. Reading it as a demand forecast is the mistake the market keeps making. Demand already converted: the doubling is a statement about how fast one process curve can climb.
Where the count begins
The ASML immersion tools that have reached mainland China support roughly 200,000 twelve-inch wafers a year, about 5 million chips before yield at current die sizes and 2 to 3 million after the usual losses. Kunpeng, Hygon and Cambricon draw from the same advanced lines, which puts the Ascend share near 1.2 million. A second count, of all die starts on domestic advanced lines, brackets the same supply from the other end: 4 to 5 million starts, around 4 million good dies, 3 to 4 million soberly.
The line that picks the year
Domestic advanced logic runs at 40 to 50% yield on the nodes that matter. The realistic path takes it above 60% in 2027, with 65 to 67% as the reference band and 70% the ceiling worth modelling; TSMC's N+1 process is understood to run near 80%, which is what a mature line looks like. On a 5 million die base, one point of yield is 50,000 chips — more than the entire first-quarter delivery of the 950DT. A plant in southern China has spent eight years on this climb and runs 40 to 60% today; the meaningful domestic capacity improvement is dated to 2028.
Three versions of 2027
| Case | Quoted 2027 shipments | Yield required | What has to be true |
|---|---|---|---|
| Conservative | 2.4M | stalls near 60% | memory pricing unresolved into the first quarter |
| Neutral | 2.8–3.0M | 65–67% | wafer allocation holds near 2026 shares |
| Optimistic | 3.3–3.5M | approaches 70% | memory clears and domestic capacity lands early |
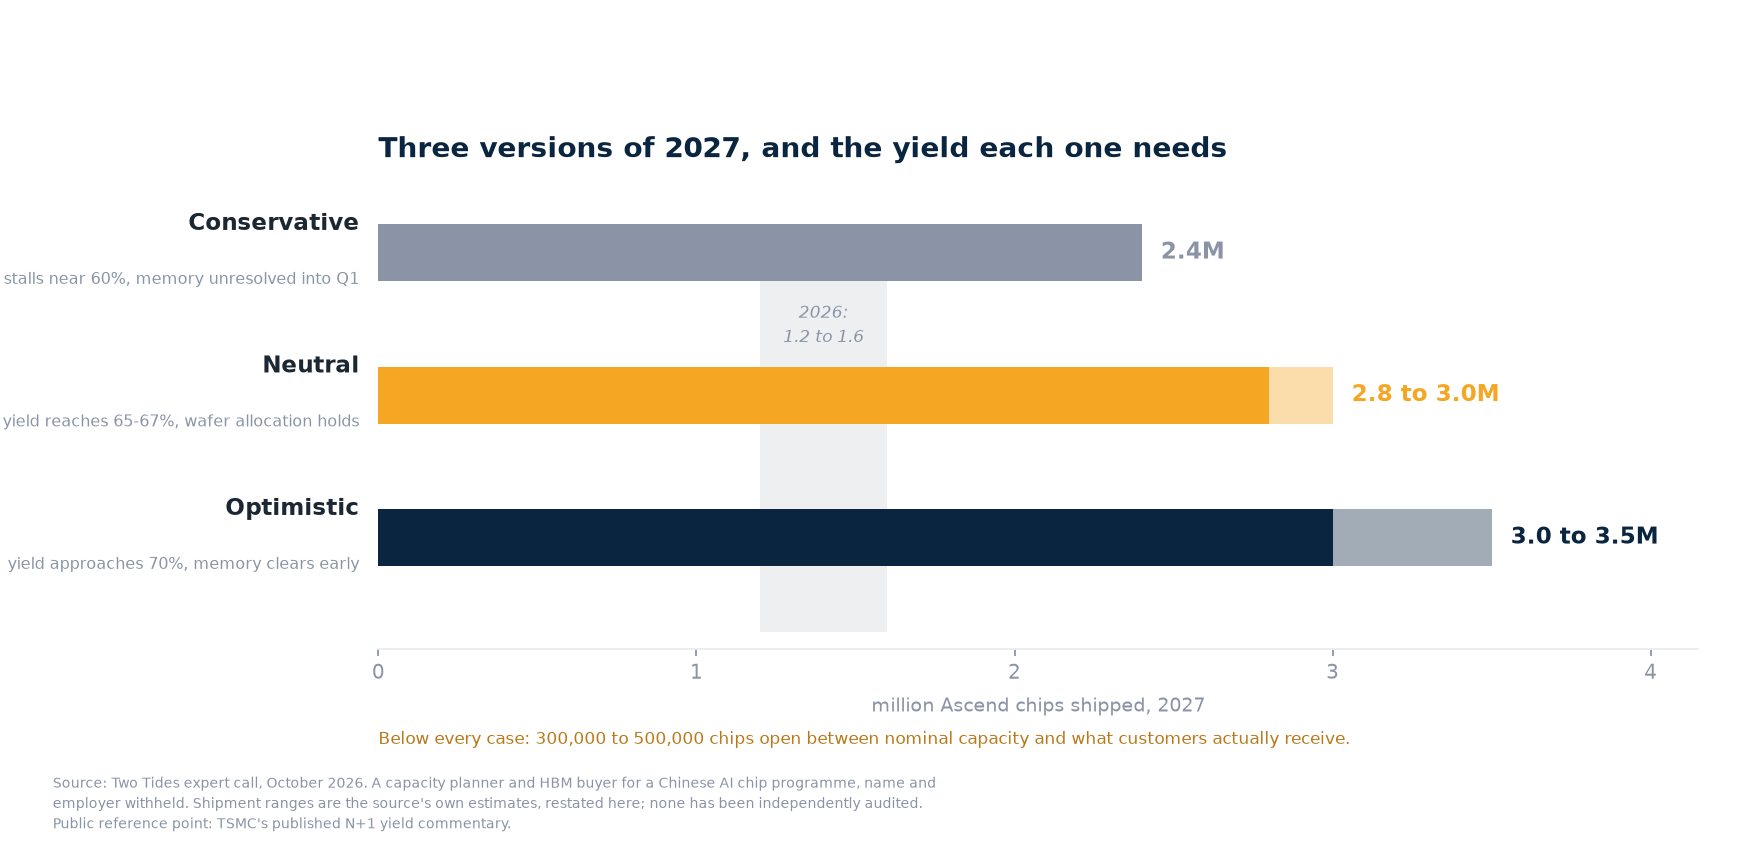
The table hides a gap. Nominal capacity in 2027, if yield improves on schedule, releases 3 to 3.5 million dies, but the same lines still carry Kunpeng, Hygon and Cambricon, and a 300,000 to 500,000 chip shortfall opens between what the lines can theoretically produce and what customers receive. Real deliveries land nearer 2.6 to 2.7 million in the neutral case and 2.4 to 2.5 million in the conservative one. On the buyer side, internet companies took 40 to 50% of 2026 shipments with a path to 50 to 60%, state buyers eased from 30 to 40% to 25 to 30% while their absolute purchases kept growing, and DeepSeek's reported 160,000-chip 950DT programme meets deliveries of 70,000 to 80,000 across late 2026 and early 2027.
Three things to check before the year turns
Fourth-quarter and first-quarter delivery numbers, where 70,000 to 80,000 chips is the honest read and anything above 100,000 means the curve is steeper than expected. Whether the memory contracts are signed before Spring Festival, because a delay pushes the 2027 build into the second half. And the yield commentary that leaks from the packaging and test houses, which see the good die rate before anyone publishes it.
The full issue walks the whole line: the 910C's second life, the memory calendar that sets the monthly cadence, the rack economics, and the second-hand price that is doing real price discovery.
Read it in Two TidesThis page is the public data companion to Two Tides Issue 007. The complete argument, including the rack roadmap and the second-hand price readout, is the issue in the letter.
Research, not advice. This page is research and commentary on an industry. It is not investment, legal or engineering advice, and not a recommendation to buy or sell any security. Figures are the best estimate available at the time of writing; where one rests on a single source, the text says so.
Cite this page as: Quorsio, "Ascend's 2027 shipment forecast: three scenarios and the yield line that picks one", November 2026, with a link to this URL. Short excerpts with attribution are welcome. Republishing the page in full, including its tables and charts, needs written permission: hello@quorsio.com.